In Old Naples, Port Royal, and Aqualane Shores, the tax question can matter more than the price negotiation. When a property bought decades ago sells for land value at today's levels, the gain can be enormous, and whether you qualify for the federal exclusion decides whether you keep an extra $250,000 or send it to the IRS. With 37 of 52 tracked older homes in the 34102 core selling off-market to builders (a 71.2% rate), many of these sales are second homes or longtime holdings, which is exactly where the tax rules get unforgiving. This guide explains the exclusion, shows where Old Naples sellers trip up, and gives you the timing moves that protect your net.
What Capital Gains Timing Means
Capital gains timing means scheduling your sale, and documenting your ownership history, so the federal home-sale exclusion shelters as much profit as the law allows. The exclusion reaches $250,000 for single filers and $500,000 for joint filers, making the calendar around closing one of the highest-value decisions in the transaction. For Old Naples sellers with decades of appreciation, timing is often the second-biggest line item after price.
Key number: $500,000. That is the maximum gain a married couple can exclude from income on the sale of a qualifying main home. "If you have a capital gain from the sale of your main home, you may qualify to exclude up to $250,000 of that gain from your income, or up to $500,000 of that gain if you file a joint return with your spouse" (Internal Revenue Service, 2025).
The timing angle exists because the exclusion depends on when you owned and lived in the home, not on how much you loved it. Miss the two-year marks by a month and the shelter shrinks or disappears. In a builder-acquisition market, where the land carries the value and gains accumulate over decades, that mistake is measured in five or six figures.
How the Two-Year Rule Actually Works
The exclusion rests on two tests, each covering two years out of the five before the sale: ownership and use. You must have owned the home at least 24 months in that window and lived in it as your main residence at least 24 months. The periods need not match, but both must fall inside the five years ending at closing. Port Royal second-home owners often fail the use test, which removes the exclusion entirely.
This is where Old Naples sellers get surprised. Port Royal and Aqualane Shores have a high concentration of second homes, and the exclusion only applies to your main home. If the Naples property was the winter house while your primary residence was elsewhere, the two-year use test fails and the full exclusion is off the table. Similarly, a longtime owner who moved out three years ago and has been renting the property since may fail the use test even though the ownership test is easily met.
Bottom line: the exclusion asks two questions, did you own it, and did you live in it, and both answers must point to the five years before closing. Map your timeline before you pick a closing date.
There is also a frequency limit: you generally cannot use the exclusion if you excluded gain on another home sale in the two years before this one. Serial movers in hot markets sometimes trigger this without realizing it.
Why Second Homes and Estates Face the Biggest Bills
In the 34102 core, older homes sold for just 25.8% of new-build prices on average. That gap is both your payday and your tax problem: the land appreciated enormously while the house aged. For a second-home owner, none of that gain is excludable. For an estate seller, stepped-up basis can reset the gain near zero. Knowing which bucket you occupy changes your after-tax net by six figures.
Consider a concrete case. A couple bought an Aqualane Shores lot with a 1960s ranch for $400,000 in 2002 and sells to a builder for $2.8 million today. The gain is roughly $2.4 million. If it was their main home for two of the last five years, $500,000 is excluded and about $1.9 million is taxable. If it was always the second home, the whole $2.4 million is taxable at capital gains rates. The difference between those two outcomes is the largest negotiation most sellers will ever conduct, and it happens with a calendar, not a buyer.
What this means for you: before you negotiate price, know which tax bucket you are in. A builder bid looks very different when you know your after-tax net.
Estates get the better deal. "The basis of property inherited from a decedent is... the FMV of the property at the date of the individual's death" (Internal Revenue Service, 2025), which means heirs who sell promptly often owe little or no capital gains tax. If you inherited the Old Naples property, your first move is a date-of-death appraisal, not a listing.
Action 1: Map Your Ownership and Use Timeline
Write out the last five years month by month and mark which months you owned the property and which months you lived in it as your main home. Count to 24 on each track. If you are close to either mark, the single highest-value move in your sale is choosing a closing date that gets you over the line. A closing delayed by six weeks can be worth $250,000 in sheltered gain.
This matters especially for sellers who recently converted a second home into a primary residence, or vice versa. The IRS does not care about your intentions, only the pattern of actual residence in the five-year window. Keep records: utility bills, voter registration, driver's license address, and tax filings all evidence where your main home was. Builders buying your lot do not care about any of this, which is precisely why it is your job to handle before the sale, not during it.
Watch out: partial exclusions exist for moves forced by work, health, or unforeseen circumstances, but they are prorated and fact-specific. Do not assume you qualify; confirm with a tax advisor before you promise yourself the number.
Action 2: Reconstruct Your Basis Before You Negotiate
Your taxable gain is sale price minus your basis, and basis is not just what you paid. It includes the purchase price plus the cost of improvements: the addition, the new roof, the seawall, the pool. In Old Naples, where homes are often held for decades, improvement records are the difference between a correct return and an overpaid one. Gather every receipt, contractor invoice, and permit record you can find before you talk price.
The math runs like this. Purchase price $400,000, plus $300,000 in documented improvements over 20 years, equals $700,000 basis. Sell for $2.8 million and your gain is $2.1 million, not $2.4 million. At a 20% capital gains rate, that $300,000 of basis documentation saves $60,000 in tax. The Collier County Property Appraiser's records can help: permit histories and prior assessments are public record (Collier County Property Appraiser, 2026), and every improvement with a permit leaves a trail.
Bottom line: your basis worksheet should be finished before your first builder conversation. Negotiating price without knowing your after-tax net is negotiating blind.
Note that lot-clearing costs, maintenance, and repairs do not add to basis. Only improvements that add value or extend the property's life count. When in doubt, your CPA makes the call.
Action 3: Time the Closing Around the Two-Year Mark
If you are within months of satisfying the ownership or use test, set the closing to land after the mark. A direct builder sale gives you day-level control over the closing date, with no lender or appraisal to move it. If your two-year ownership anniversary is March 15, you close March 20 and the exclusion holds. When the wait is weeks and the shelter is six figures, take the wait.
This is one of the quiet advantages of selling off-market. In a listed sale, the closing date is at the mercy of the buyer's lender, the appraisal, and the inspection renegotiation. In a direct builder sale, the date is a contract term you choose. If your two-year ownership anniversary is March 15, you close March 20, and the exclusion is intact.
Key number: 24 months. That is the ownership threshold and the use threshold. Count them precisely, because the IRS does.
One caution: do not let the tax tail wag the price dog. If waiting three months for the exclusion costs you a committed builder buyer in a softening market, the trade is usually bad. But when the wait is weeks and the shelter is six figures, take the wait.
Comparison: Selling With and Without the Exclusion
The exclusion is the single biggest variable in many Old Naples transactions, swinging after-tax proceeds by more than the spread between competing builder bids. The table below lays out the five common tax situations, from full joint exclusion to inherited stepped-up basis, with what each means for your net and where each strategy breaks down.
| Situation | Tax Treatment | Best For | Limitation |
|---|---|---|---|
| Main home, both tests met, joint filers | Up to $500,000 of gain excluded | Longtime resident sellers | Gain above $500,000 still taxable |
| Main home, both tests met, single filer | Up to $250,000 excluded | Single longtime residents | Same structure, half the shelter |
| Second home, never primary | No exclusion; full gain taxable | N/A, this is the costly bucket | Consider 1031 exchange into investment property instead |
| Inherited property | Basis stepped up to date-of-death FMV | Heirs selling promptly | Get the date-of-death appraisal; delays can create new gain |
| Partial exclusion (work/health move) | Prorated exclusion | Sellers forced to move early | Requires qualifying event and documentation |
Bottom line: your tax bucket can swing your net by more than the spread between competing builder bids. Know your bucket first.
The second-home row deserves emphasis. Many Old Naples sellers assume the exclusion follows the property. It follows the person and the pattern of residence. If 34102 was the winter house, plan for the full tax bill and price accordingly, or explore a 1031 exchange with a qualified intermediary before closing.
How to Choose Your Timing Strategy
Your timing strategy should follow your ownership history, not market chatter or a builder's preferred schedule. The table below maps the situations Old Naples sellers actually face, from passing both tests cleanly to discovering the property was always a second home, to the closing-date move that fits each one.
| Situation | Recommended Approach |
|---|---|
| You have lived here 2+ of the last 5 years | Close after confirming both tests; claim the full exclusion |
| You are 3 to 6 months short of a test | Delay closing past the mark via contract date; direct sales allow this |
| This was always the second home | Price for the full tax bill; evaluate a 1031 exchange with your advisor |
| You inherited the property | Get a date-of-death appraisal immediately; sell promptly to lock in the stepped-up basis |
| You already used the exclusion on another sale within 2 years | Wait out the frequency limit if the numbers justify it |
| You are unsure which bucket you are in | See a CPA before signing anything; the answer is worth more than the consultation |
A similar timing logic applies in other Florida builder-demand pockets. In Downtown Boca, where 32 of 44 tracked older homes were acquired by builders off-market at a 72.7% rate, longtime owners face the same second-home and basis questions; the Boca batch-3 guide covers lot-clearing timing there, while this guide handles the tax side. Compare approaches in the Downtown Boca batch-3 guide.
Frequently Asked Questions
These are the capital gains questions Old Naples sellers ask most, answered directly. They cover the two-year rule, second-home treatment, inherited basis, reconstructing improvement records, and whether the buyer's identity changes the tax math. Tax law is fact-specific, so confirm your situation with a CPA before you sign.
How long do I have to live in my house to avoid capital gains tax?
You must have owned it for at least two years and lived in it as your main home for at least two years, both within the five years before the sale. Meet both tests and you can exclude up to $250,000 of gain, or $500,000 filing jointly.
Does the exclusion apply if the Old Naples house was my second home?
The exclusion only applies to your main home, the one you live in most of the time, so a winter house in Port Royal that was never your primary residence gets no exclusion. A 1031 exchange into investment property may defer the tax instead, so discuss that path with your advisor before closing.
I inherited the house. Do I owe capital gains tax when I sell?
Usually very little, because your basis is stepped up to the fair market value at the date of death (Internal Revenue Service, 2025). Sell near that value and the taxable gain is close to zero, but get a date-of-death appraisal to prove it.
What counts toward my basis besides the purchase price?
Improvements that add value or extend the property's life: additions, new roofs, pools, seawalls, major systems. Routine repairs and maintenance do not count, so keep contractor invoices and permit records for everything that qualifies.
Can I exclude gain if I already used the exclusion on another home?
Generally not if you excluded gain on another sale within the two years before this one. This frequency limit catches serial movers, so check your sale history before counting on the shelter.
What if I am a few months short of the two-year use test?
Delay the closing, because in a direct builder sale you control the closing date as a contract term and pushing it past the anniversary is straightforward. Six weeks of patience can be worth up to $250,000 in excluded gain, which is the highest-paid waiting most sellers will ever do.
Do I pay Florida state capital gains tax on top of federal?
Florida has no state income tax, so there is no state-level capital gains tax on your sale. Your tax bill is federal only, which is one reason after-tax nets here compare favorably to high-tax states.
Does selling to a builder change the tax treatment?
The tax rules depend on your ownership and use history, not on who buys, so a builder purchase is taxed exactly like a sale to a family. The direct format does give you one advantage: precise control over the closing date, which is what makes tax timing possible.
What is a 1031 exchange and does it work for a second home?
A 1031 exchange lets you defer capital gains by rolling proceeds into a like-kind investment property. It works for investment property, not personal-use second homes, so talk to a qualified intermediary before closing if this path interests you.
Should I talk to a CPA before accepting a builder offer?
Yes, if the gain is large or your situation is anything other than a straightforward longtime primary residence. The consultation costs a few hundred dollars and routinely changes the answer by five or six figures.
How Legacy Off-Market Sources Your Off-Market Deal to Builders
Legacy Off-Market is a wholesaler: we buy your property directly off-market, then place the deal with vetted builders from our buyer network. That structure is built for tax-timed closings, because our purchase needs no lender timeline or appraisal contingency that could move your date. Your closing lands after your two-year marks by contract; we handle the placement with builders afterward.
The five advantages over a traditional listing are measurable. Privacy: zero showings, zero open houses, no public marketing period, which matters in a neighborhood where discretion is the norm. Timing: close in 7 to 21 days when speed matters, set an exact future date when the tax calendar requires it, or use a leaseback, versus 60 to 120-plus days for a listed older home. No commissions: none of the typical 5 to 6% sellers pay (National Association of Realtors, 2025). No closing costs: none of the usual 1 to 2% in seller-side costs; on a seven-figure Old Naples transaction the savings scale into six figures. No inspections or repairs: no $10,000 to $30,000 in repair credits or price reductions, because the lot is what is being valued and the structure transfers as-is.
Call 401-219-4207 or email aidansowa@outlook.com to map your ownership timeline against a closing date. Confirm your property is in the coverage area, and read how the methodology works to see how the builder-demand data behind this guide was compiled.
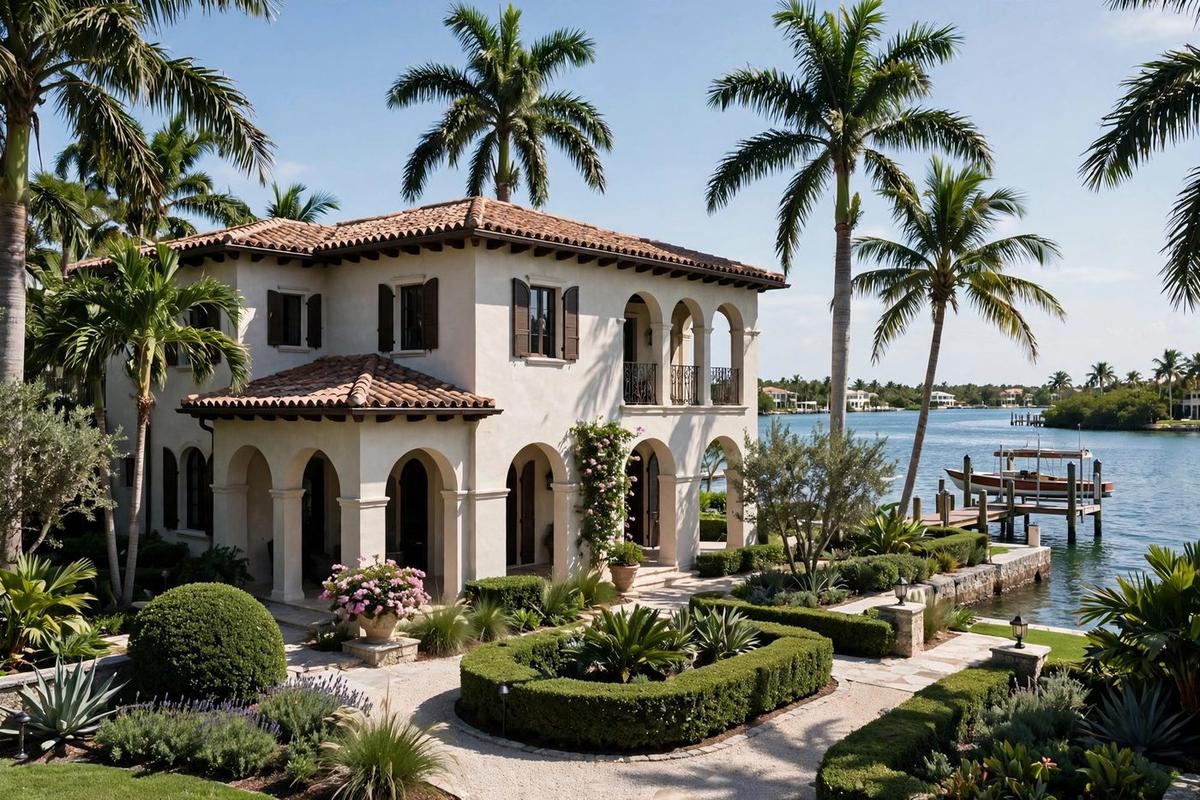
A luxury Mediterranean waterfront estate in Old Naples, where a builder acquisition can turn a longtime holding into a tax-timed closing.
Sources
- Legacy Off-Market, 2026. Builder-demand study: ZIP 34102 sample, 52 older homes, 37 acquired by builders off-market (71.2%), older homes at 25.8% of new-build prices. Market data.
- Internal Revenue Service, 2025. Topic 701, Sale of Your Home: $250,000/$500,000 capital gain exclusion rules. Government data.
- Internal Revenue Service, 2025. Publication 551, Basis of Assets: inherited property basis rules. Government data.
- National Association of Realtors, 2025. Profile of Home Buyers and Sellers. Industry report.
- Collier County Property Appraiser, 2026. Permit histories and prior assessment records. Official record.